PMMY Eligibility Criteria Explained 2026: You may already know what you want to do—open a shop, buy a sewing machine or give your small business room to grow. Finding the money is often the difficult part. Pradhan Mantri Mudra Yojana (PMMY) allows eligible micro-businesses to apply for collateral-free loans through participating banks, NBFCs and MFIs.
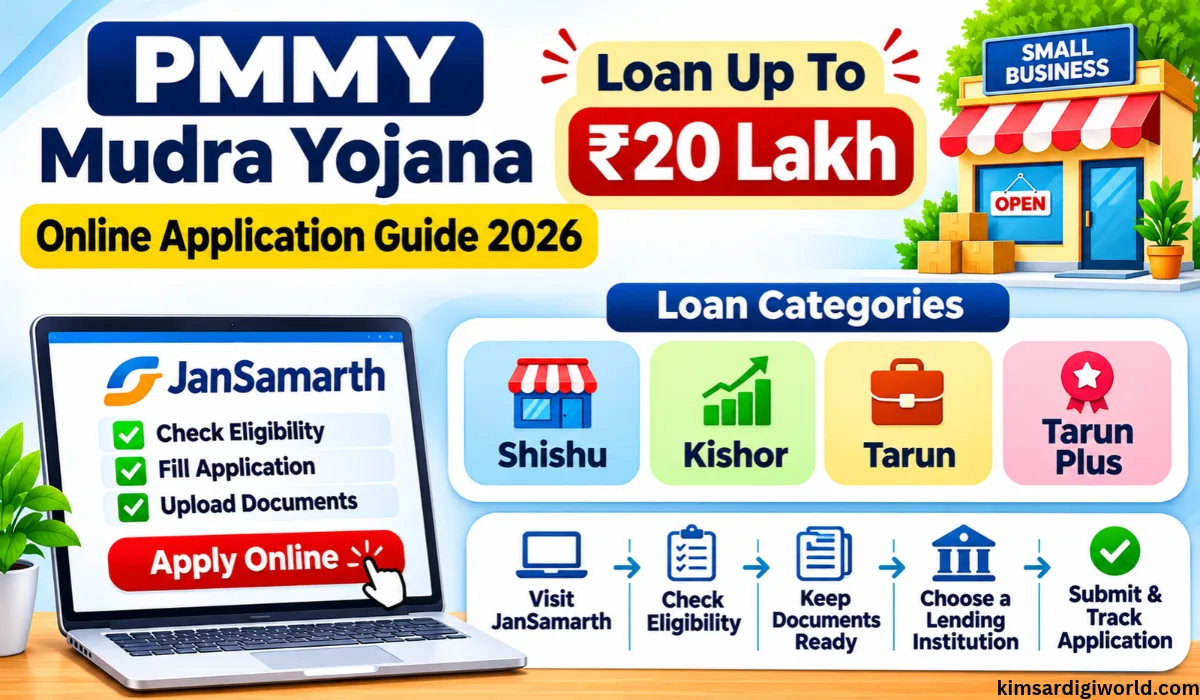
But before you start collecting documents, check whether your business fits the scheme. Mudra loans go up to ₹20 lakh, although amounts above ₹10 lakh fall under Tarun Plus, which is reserved for borrowers who have successfully repaid an earlier Tarun loan. Here’s how eligibility works for new entrepreneurs and existing business owners.
PMMY Eligibility Criteria Explained 2026: Overview
- Scheme: Pradhan Mantri Mudra Yojana (PMMY).
- Eligible applicants: Individuals and eligible business entities.
- Business type: Income-generating non-farm micro-enterprises, including eligible allied agricultural activities.
- Eligible sectors: Manufacturing, trading and services.
- Loan amount: Up to ₹20 lakh, subject to category-specific conditions.
- Age limit: Depends on the lending institution’s requirements.
- Collateral: Not required under the scheme.
- Application mode: Online where available, or through participating lending institutions.
Who Can Apply for a Mudra Loan?
You don’t need to own a large company to apply. Mudra loans are meant to support eligible small businesses, including people taking their first steps into self-employment.
Applicants may include:
- First-time entrepreneurs with a workable business proposal.
- Existing small business owners looking to grow.
- Shopkeepers, traders and retailers.
- Small manufacturers and service providers.
- Proprietorship and partnership businesses.
- Eligible companies and other business entities, subject to the scheme’s scope.
- Women entrepreneurs starting or expanding a business.
Having a business idea is the starting point. The lender will also want to understand how it will earn money and how you expect to repay the loan.
Mudra Loan Age Limit 2026
Don’t assume an age range quoted online applies to every Mudra lender. Age requirements can differ between lending institutions, including how they assess your age at application or at the end of the repayment period.
Ask your chosen lender about its requirements before preparing the full application. That small check can save an unnecessary trip.
Eligible Business Activities Under Mudra Yojana
Mudra loans support income-generating work in manufacturing, trading, services and eligible activities allied to agriculture. That includes many familiar businesses serving everyday needs.
| Manufacturing | Small production units and food processing |
| Trading | Grocery shops and retail stores |
| Services | Tailoring, repair shops and salons |
| Transport | Eligible commercial vehicle businesses |
| Allied Agriculture | Dairy, poultry and beekeeping |
The purpose of the borrowing matters. Ordinary crop loans and general personal expenses are not covered under PMMY.
Mudra Loan Eligibility for New Businesses
Starting from scratch does not automatically rule you out. First-time entrepreneurs can apply if they have an eligible, workable business proposal.
For example, you might want to:
- Open a grocery shop.
- Start a tailoring business or beauty parlour.
- Set up a small manufacturing unit.
- Run a repair or service centre.
- Begin an eligible dairy or poultry business.
You don’t have to pretend the business is already successful. You do need to explain what you plan to sell, what it will cost to get started and how the income could cover repayments. The lender will assess those details before deciding.
Mudra Loan Eligibility for Existing Businesses
Perhaps your shop is running, but you keep running out of stock. Or your orders have grown beyond what one old machine can handle. Existing micro-businesses can also apply for eligible business funding.
The loan may help with:
- Buying machinery or equipment.
- Purchasing business tools.
- Meeting working-capital needs, such as eligible stock and operating expenses.
- Increasing production or service capacity.
- Expanding existing operations.
Be clear about what the money will change. The lender will assess both the purpose of the loan and your business’s ability to repay it.
Tarun Plus Loan Eligibility
The ₹20 lakh limit can catch your attention, but there’s an important condition behind it. Tarun Plus covers loans above ₹10 lakh and up to ₹20 lakh—not a ₹20 lakh starting limit for every applicant.
To qualify for consideration:
- You must have previously taken a Tarun-category loan.
- You must have successfully repaid that loan.
- You must meet the lender’s other requirements.
If you have never taken and successfully repaid a Tarun loan, you cannot directly enter through Tarun Plus. Even eligible repeat borrowers must go through the lender’s assessment.
Who May Not Qualify for a Mudra Loan?
A rejection can be disappointing, especially when you’ve already made plans for the money. Knowing the possible reasons can help you spot problems before applying.
An application may not be approved if:
- The proposed business activity is not eligible.
- The money is intended for personal or non-business expenses.
- Important information is missing, incorrect or inconsistent.
- The applicant has a poor repayment record or unresolved defaults.
- The proposed borrowing does not appear affordable.
- The applicant does not meet the chosen loan category’s conditions.
- Other lending requirements are not met.
Meeting the basic eligibility rules does not guarantee approval. If the lender declines your application, ask for the specific reason before applying again.
Does a CIBIL Score Matter for a Mudra Loan?
There isn’t one universal CIBIL score cut-off that should be quoted as the rule for every PMMY application. But that doesn’t mean credit history is ignored. Banks and other lenders may check previous borrowing, missed payments, and outstanding dues. Existing defaults can make approval harder.
Having no credit history is different from having a poor one. If you’ve never borrowed before, ask how the lender assesses first-time borrowers rather than assuming you cannot apply.
Important Links
| MUDRA Official Website | Check Here |
| JanSamarth Loan Portal | Check Here |
| PMMY Eligibility & Scheme Details | Check Here |
| Department of Financial Services | Check Here |
FAQs on PMMY Eligibility Criteria Explained 2026
Who is eligible for a Mudra loan?
Individuals and eligible business entities with qualifying income-generating micro-business activities can apply. Approval depends on the business proposal, loan category and lender’s requirements. Loans above ₹10 lakh require Tarun Plus eligibility.
Can an unemployed person apply for a Mudra loan?
Yes. Not having a salaried job does not automatically disqualify you. You’ll need an eligible business proposal and must satisfy the lender that the planned business can support repayment.
Can I get a Mudra loan to start a new business?
Yes. New businesses can be considered, subject to eligibility and the lender’s assessment. Explain what you want to start, how much you need and how you expect to earn from it.
Is there an age limit for a Mudra loan?
Lenders set the age limit. If you can’t find the age limit on the web, read the terms before applying.
Can women apply for a Mudra loan?
Absolutely. PMMY also allows women to establish or expand eligible firms. However, this is subject to approval as per the scheme and terms of finance.
Can I apply for a Mudra loan without a CIBIL score?
Even if you do not have a credit score, you will not be excluded as it is not an eligibility criterion under the system. However, they will take into account your financial history, your ability to pay, and your existing credit.
Disclaimer: This article provides general eligibility guidance, not a promise of loan approval. Confirm current scheme conditions and lender-specific requirements with the participating institution before applying.