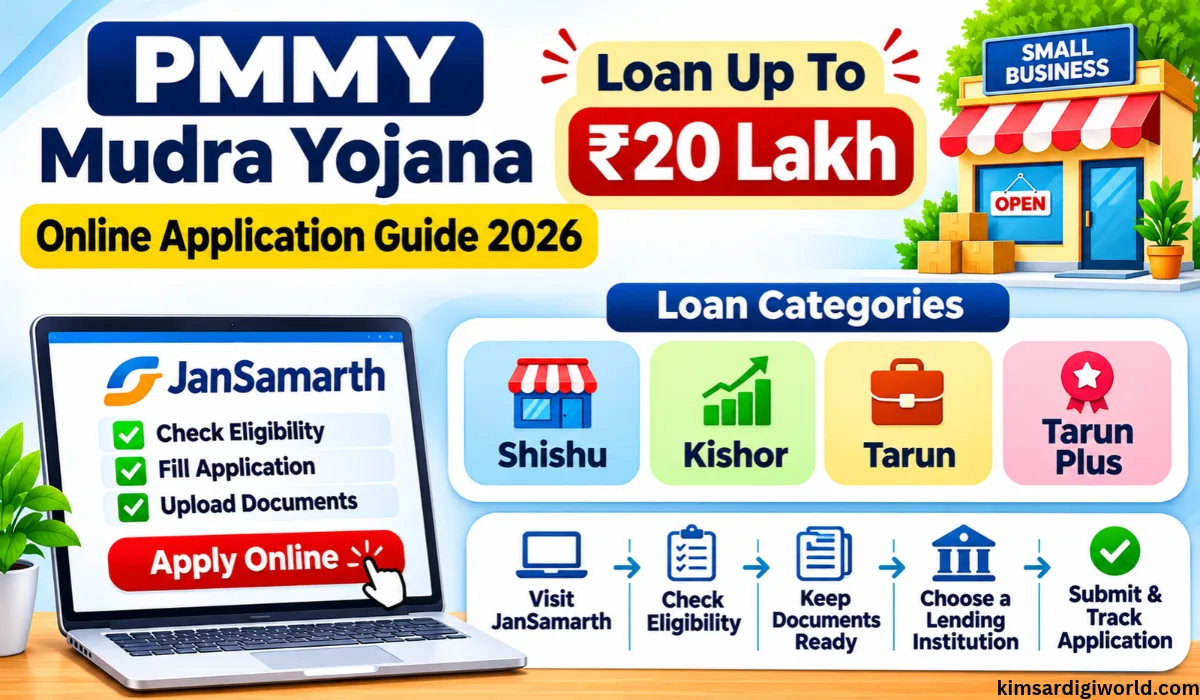
PMMY Online Application Guide 2026: Maybe your shop needs more stock. Maybe an old machine is slowing down orders. Or perhaps you’re ready to start a business but don’t have enough savings to take that first step. Pradhan Mantri Mudra Yojana (PMMY) helps eligible small businesses access collateral-free loans through participating lenders.
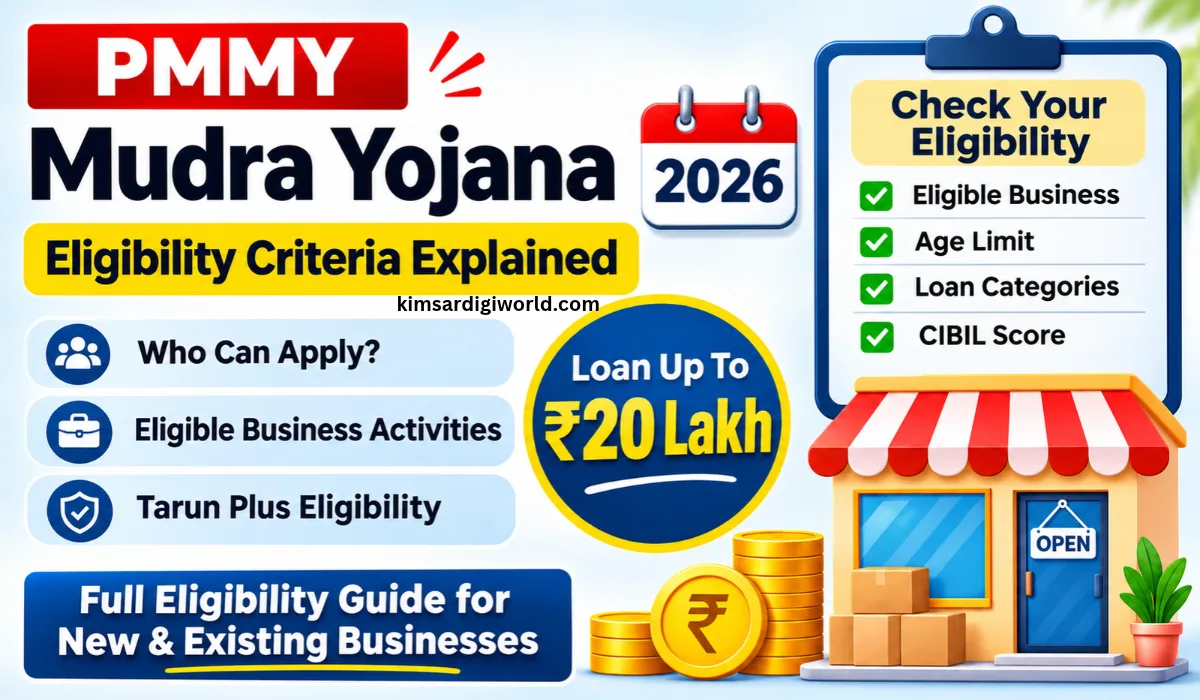
You can check eligibility and begin an application through JanSamarth, or approach a participating bank, NBFC or MFI. Loans can go up to ₹20 lakh, but that upper limit comes with a condition: amounts above ₹10 lakh fall under Tarun Plus, for borrowers who have successfully repaid an earlier Tarun loan. Here’s how to apply and what to expect along the way.
PMMY Online Application Guide 2026: Overview
- Scheme: Pradhan Mantri Mudra Yojana (PMMY).
- Loan amount: Up to ₹20 lakh, subject to loan-category conditions.
- Loan categories: Shishu, Kishor, Tarun and Tarun Plus.
- Application portal: JanSamarth.
- Application mode: Online and offline.
- Eligible applicants: Individuals and eligible business owners with qualifying business activities.
- Lending institutions: Participating banks, NBFCs and MFIs.
- Collateral: Not required under the scheme.
How to Apply for a Mudra Loan Online?
You can begin through JanSamarth. The exact screens, menu names and available lending options may change, so follow the instructions currently displayed on the official portal.
Step 1: Visit the JanSamarth Portal
Open jansamarth.in. or https://www.jansamarth.in/ and look for the registration or sign-in option.
Use a mobile number you can access and complete the requested verification. Provide an email address if the current process asks for one. Keep access to these contact details—you may need them for application updates.
Step 2: Check Your Eligibility
Find the business-loan schemes section and select PMMY, where available. Answer the eligibility questions using your actual business details and funding needs.
Take your time here. An eligibility result can help you understand whether to proceed, but it is not a promise of loan approval.
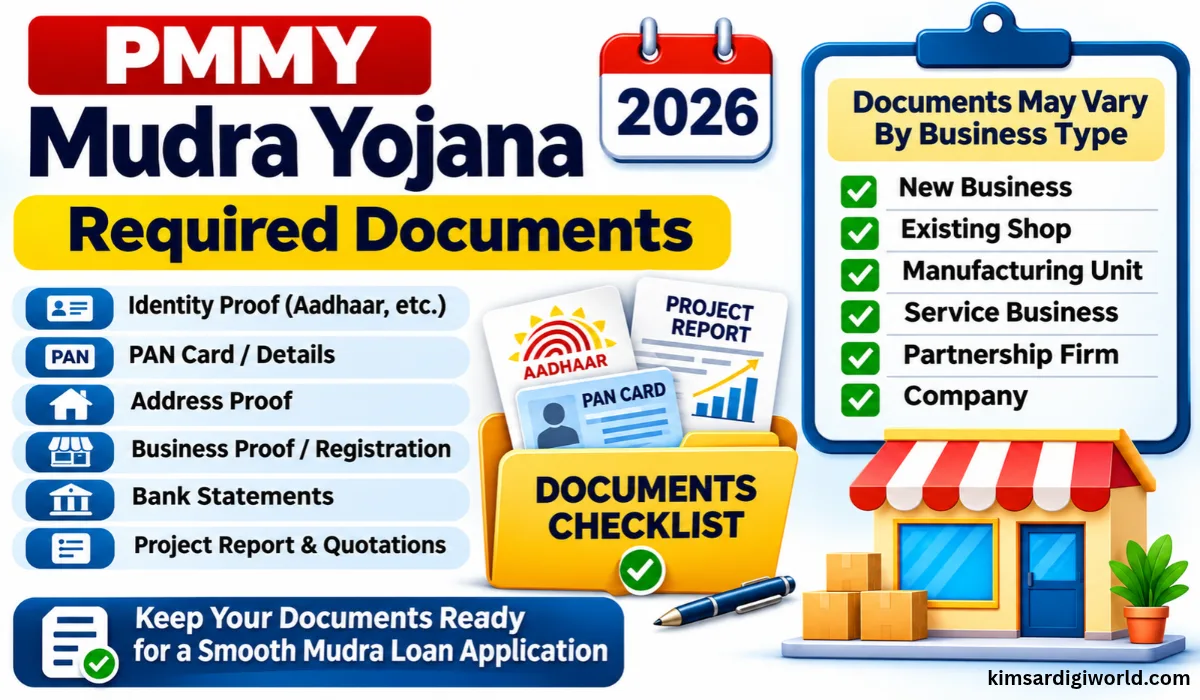
Step 3: Keep Your Documents Ready
Follow the checklist shown for your application. Depending on your business and loan proposal, it may ask for:
- Aadhaar or other accepted KYC documents.
- PAN details or permitted documentation, as applicable.
- Udyam registration details, where required.
- Bank account details and statements.
- Business, sales and income information.
- A project report, quotations or other supporting documents.
Note: Don’t assume another applicant’s checklist will match yours. A new tailoring business and an established workshop may need different paperwork.Step 4: Complete Applicant Verification
Enter the requested personal and business information, then complete the available verification steps. These may involve Aadhaar, PAN, Udyam, GST or financial records, depending on your application. Read the consent requests before agreeing, and check any information fetched automatically.
If something is wrong, don’t rush past it. Follow the portal’s correction instructions or ask the lender how to proceed.
Step 5: Enter Business and Loan Details
This is where you explain what the money will actually do for your business.
You may need to provide:
- Business name and address.
- Type of business activity.
- How long the business has been operating, if applicable.
- Loan amount requested.
- Purpose of the borrowing.
- Machinery or equipment details, where relevant.
- Estimated income and expenses.
Use realistic figures. If you need money for stock, equipment and working expenses, separate those costs rather than entering a round number without an explanation.
Step 6: Select a Lending Institution
Review the participating lenders or options displayed for your application. Choose a suitable institution and branch, where the portal allows you to do so. Look beyond the loan amount. Check the interest rate, repayment period, instalment amount and applicable charges. If a term is unclear, ask before accepting it.
Not every applicant will necessarily see the same lenders or offers.
Step 7: Submit Your Application
Before submitting, check your name, bank details, business information and requested loan amount once more.
Complete any remaining requirements, submit the form and save your application reference number. Use your dashboard to watch for updates or requests for additional documents.
Important: Submission, an eligibility result or an in-principle offer is not the same as final sanction or payment. The lender may carry out further checks, and disbursement happens only after the required conditions are met.How to Apply for a Mudra Loan Offline?
If the online process feels difficult—or you’d rather discuss your business in person—you can approach a participating lender directly.
- Visit a bank, NBFC or MFI that offers Mudra loans.
- Ask for the current PMMY application form and document checklist.
- Discuss the loan category that fits your requirements and eligibility.
- Fill in your personal and business details.
- Attach the requested documents.
- Submit the application to the person handling business loans.
- Collect an acknowledgement or reference number.
- Ask how to follow up and respond to any further requests.
Before leaving, check whether anything is missing. It’s easier to sort out a document question there than discover it after another week of waiting.
What Happens After Submitting a Mudra Loan Application?
Once the application reaches the lender, the focus shifts to your business and whether the proposed borrowing is manageable.
The assessment generally includes:
- Checking your identity and business details.
- Reviewing why you need the loan.
- Assessing income, expenses and repayment capacity.
- Requesting clarification or extra documents, if needed.
- Deciding whether to approve the loan.
- Releasing funds after the required formalities are completed.
A request for more information does not automatically mean rejection. Respond carefully, and keep copies of what you submit.
How to Check Mudra Loan Application Status?
Start with the same channel you used to apply.
- JanSamarth applicants: Sign in and look for My Applications or the section showing submitted applications.
- Bank applicants: Contact the branch handling your case with your reference number.
- NBFC/MFI applicants: Use the institution’s official customer service or application-tracking channel.
If the status hasn’t changed, ask: “Is anything pending from my side?” That can get you a more useful answer than simply asking how much longer it will take.
Important Points Before Applying
- Use official portals and participating lenders. Avoid unfamiliar forms shared through messages.
- Keep your documents ready. Clear, consistent records can prevent avoidable follow-ups.
- Choose a suitable loan category. The maximum scheme limit is not automatically available to everyone.
- Be honest about income and expenses. Borrowing should support the business, not leave it struggling with repayments.
- Read the loan terms. Check interest, instalments, tenure and charges.
- Don’t trust guaranteed-approval promises. An unofficial agent cannot override the lender’s decision.
- Save your acknowledgement. You’ll need it if you have to trace or follow up on the application.
Important Links
| JanSamarth Application Portal | Apply Online |
| MUDRA Official Website | Check Here |
| PMMY Scheme Details | Check Here |
| Department of Financial Services | Check Here |
FAQs on PMMY Online Application Guide 2026
How can I apply for a Mudra loan online?
Start at JanSamarth, check the PMMY eligibility questions and follow the application instructions. Keep your business details and documents nearby so you’re not searching for them halfway through.
Is JanSamarth the official portal for Mudra loan applications?
Yes. JanSamarth is a government portal where you can check PMMY eligibility and begin an application. Make sure you’re on jansamarth.in, not a lookalike website promising easy approval.
Can I apply for a Mudra loan without visiting a bank?
You can get started from home through JanSamarth. Just don’t assume the whole process will stay online—the lender may ask you to bring documents to a branch or complete further checks.
Can I apply for a Mudra loan offline?
Yes. If you’d rather talk through your business plans in person, visit a participating bank, NBFC or MFI. Call ahead to check whether it handles Mudra loans and what papers to bring—it could save you a second trip.
What is the maximum loan amount under PMMY?
The maximum is ₹20 lakh under Tarun Plus. Loans above ₹10 lakh are for eligible borrowers who have successfully repaid a previous Tarun loan, and approval still depends on the lender’s assessment.
Disclaimer: This article explains the general application process. Portal steps, document requirements and lending terms may change. Confirm the current instructions with JanSamarth or your chosen participating lender before applying. Eligibility or application submission does not guarantee approval.