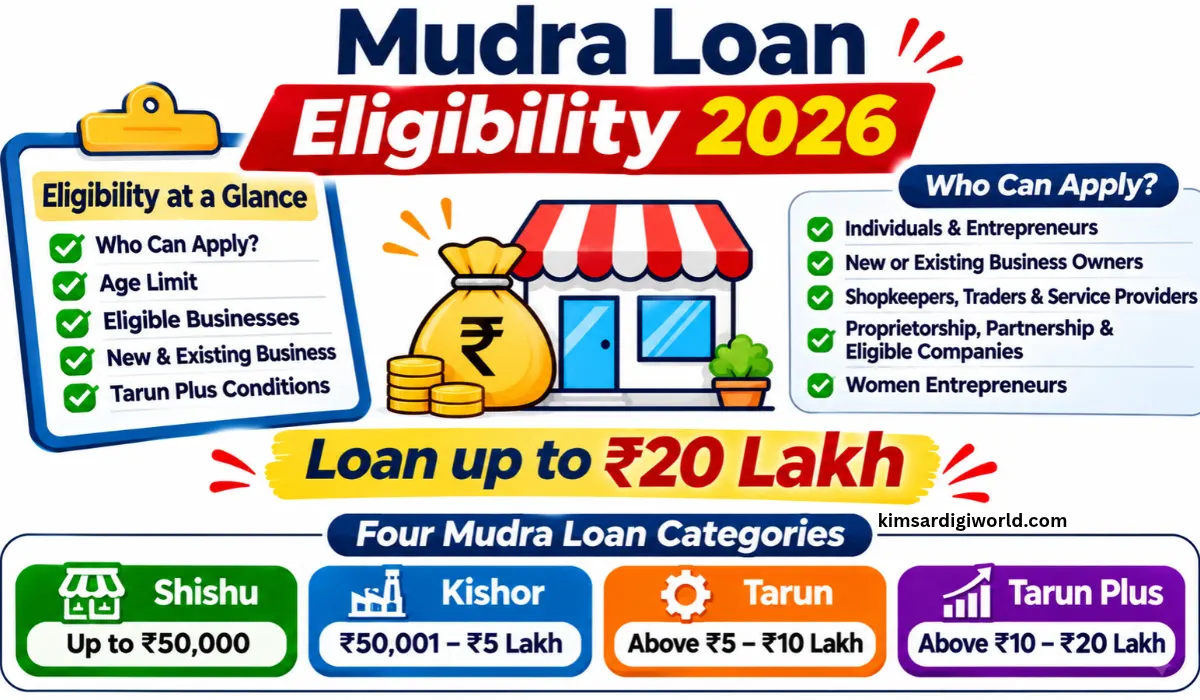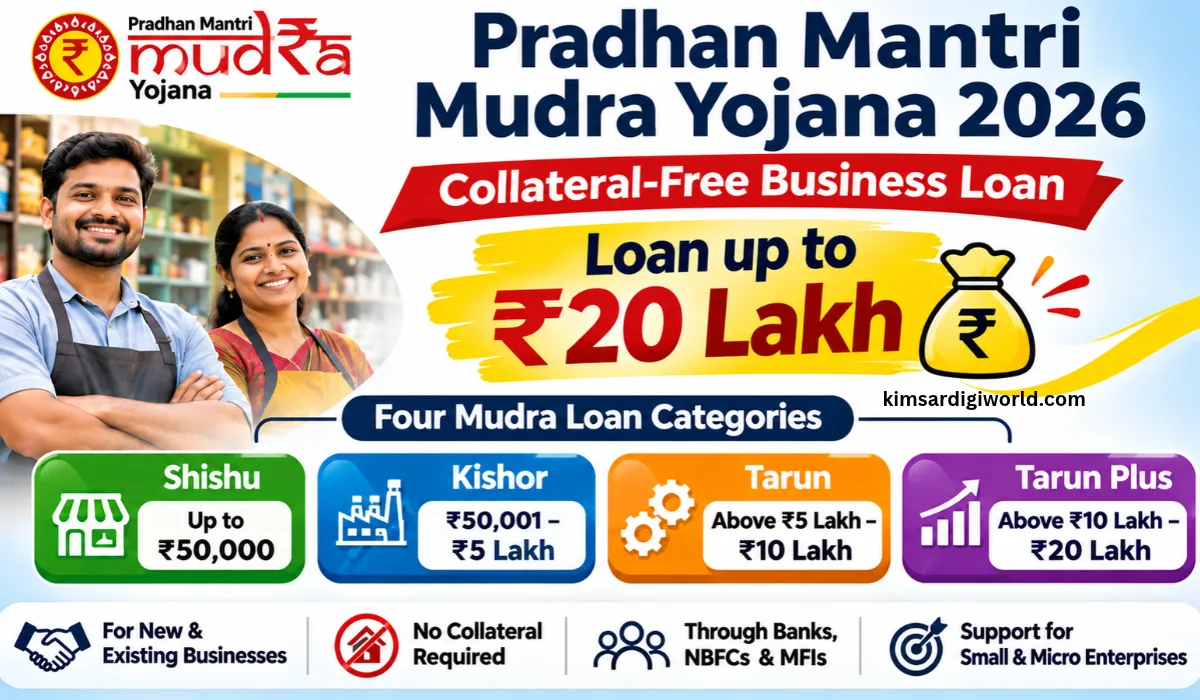
Mudra Loan Eligibility 2026: And if you are looking to start a small business or a new venture, then you have to first check out the Mudra loan eligibility. And then, as part of Pradhan Mantri Mudra Yojana (PMMY), eligible businesses can apply for business loans of Rs 10 lakhs with banks, NBFCs & MFIs with absolutely zero collateral at all.
You should be a first-time entrepreneur/shopkeeper/small-scale manufacturer/service provider or meet other business criteria under the scheme. Mudra Loan Eligibility 2026: Age, Business, Qualifications, and more.
Mudra Loan Eligibility 2026: Overview
- Scheme: Pradhan Mantri Mudra Yojana (PMMY)
- Eligible Applicants: Individuals and eligible business entities
- Business Type: Non-farm micro-enterprises
- Eligible Sectors: Manufacturing, trading and services
- Loan Amount: Up to ₹20 lakh
- Age Limit: Subject to lending institution requirements
- Collateral: Not required under the scheme
- Application Mode: Online or through participating lending institutions
Who Can Apply for a Mudra Loan?
Individuals and eligible business entities involved in income-generating micro-business activities can apply for a Mudra loan.
The following applicants may be eligible:
- Individual entrepreneurs planning to start a business.
- Existing small business owners.
- Shopkeepers, traders and retailers.
- Small manufacturers and service providers.
- Proprietorship and partnership businesses.
- Eligible companies and other business entities.
- Women entrepreneurs starting or expanding a business.
Note: Applicants must have a viable business proposal and meet the lending institution's requirements.Mudra Loan Age Limit 2026
There is no age limit for all applicants under PMMY. The age limits may vary from bank to bank and lender to lender.
Applicants should confirm the lender’s age eligibility criteria before submitting the application.
Eligible Business Activities Under Mudra Yojana
Mudra loans support income-generating activities in manufacturing, trading, services, and eligible allied agricultural sectors.
| Manufacturing | Small factories, food processing |
| Trading | Grocery shops, retail stores |
| Services | Tailoring, repair shops, salons |
| Transport | Eligible commercial vehicle businesses |
| Allied Agriculture | Dairy, poultry, beekeeping |
The scheme does not cover ordinary agricultural crop loans or general personal expenses.
Mudra Loan Eligibility for New Businesses
Yes, first-time entrepreneurs can apply for a Mudra loan if they have a viable business proposal.
Some examples include:
- Starting a grocery or retail shop.
- Opening a tailoring or beauty parlour.
- Setting up a small manufacturing unit.
- Starting a repair or service centre.
- Establishing an eligible dairy or poultry business.
The lending institution will assess the business plan, financial requirements and repayment capacity before approving the loan.
Mudra Loan Eligibility for Existing Businesses
Existing micro-business owners can also apply for financial assistance to meet eligible business requirements.
The loan may be used for:
- Purchasing machinery or equipment.
- Buying business-related tools.
- Arranging working capital.
- Increasing business capacity.
- Expanding existing operations.
The proposed loan must meet the scheme’s requirements and the lender’s credit assessment.
Tarun Plus Loan Eligibility
Tarun Plus is the highest Mudra loan category, offering financial assistance above ₹10 lakh and up to ₹20 lakh.
However, it has an additional eligibility condition:
- The applicant must have previously availed a Tarun-category loan.
- The previous Tarun loan must have been successfully repaid.
- The applicant must meet the lending institution’s other requirements.
First-time applicants who have never taken and repaid a Tarun loan cannot directly apply under Tarun Plus.
Who May Not Qualify for a Mudra Loan?
An application may be rejected if the applicant:
- Does not have an eligible income-generating business proposal.
- Seeks funds for personal or non-business expenses.
- Provides incomplete or incorrect information.
- Has an unsatisfactory credit or repayment record.
- Cannot satisfy the lending institution’s assessment requirements.
- Does not meet the applicable loan-category conditions.
Meeting the basic scheme criteria does not guarantee loan approval.
Does a CIBIL Score Matter for a Mudra Loan?
A CIBIL score is not a single universal eligibility cut-off prescribed for all PMMY applicants. However, banks and other lending institutions may check the applicant’s credit history and repayment behaviour while assessing the loan proposal.
Applicants with existing loan defaults or poor repayment records may face difficulties obtaining approval.
Important Links
| MUDRA Official Website | Check Here |
| JanSamarth Loan Portal | Check Here |
| PMMY Eligibility & Scheme Details | Check Here |
| Department of Financial Services | Check Here |
FAQs on Mudra Loan Eligibility 2026
Who is eligible for a Mudra loan?
Any Indian Citizen who has a business plan for an income-generating non-farm activity (such as manufacturing, processing, commerce or service industry) and whose credit need is less than Rs 10 lakh can approach a Bank, MFI or NBFC for availing of Mudra loan.
Can an unemployed person apply for a Mudra loan?
Yes, an unemployed person can apply as long as he/she is ready to create a business falling under the program and lending institution.
Can I get a Mudra loan to start a new business?
Yes. A good company idea for new startups to start.
Is there an age limit for a Mudra loan?
There is no maximum age limit for PMMY for all. The age limit is determined by the lender the applicant has approached.
Can women apply for a Mudra loan?
Yes. PMMY is a co-support strategy for women entrepreneurs on the financial front.
Can I apply for a Mudra loan without a CIBIL score?
PMMY does not require you to have a CIBIL score. However, there may be checks by the lending bank on your financial and credit background.
Disclaimer: The lending institution will decide whether or not to approve and offer the Mudra loan to the applicant, based on the criteria set under the scheme. Check with the scheme’s lender before applying.